Meaning
This financial accounting and supply chain practice involves allocating a specific fund to account for the reduction in value of stored battery inventory over time. Referred to as an inventory depreciation reserve, this fund compensates for both the physical degradation of the cells and the market price drops of newer technology. It establishes a realistic valuation of the asset on the company balance sheet, preventing the overvaluation of aging stock.
This financial tool governs the inventory management and auditing processes of battery distributors, pack assemblers, and system integrators. It stops applying once the affected inventory is either sold, written off, or deployed.
Financial Mechanism
The calculation of this reserve is based on the age of the inventory and the known rate of chemical degradation of the stored cells. As lithium-ion batteries sit in storage, they undergo calendar aging, which permanently reduces their capacity and increases their internal resistance. This physical deterioration reduces the market value of the cells, as they can no longer meet the performance specifications of fresh inventory.
In addition, rapid advancements in battery technology and falling manufacturing costs make older cell models less competitive over time. The company adjusts this financial buffer at regular intervals to reflect these combined losses in value. This adjustment ensures that the reported value of the inventory aligns with its true market worth.
Inventory Management
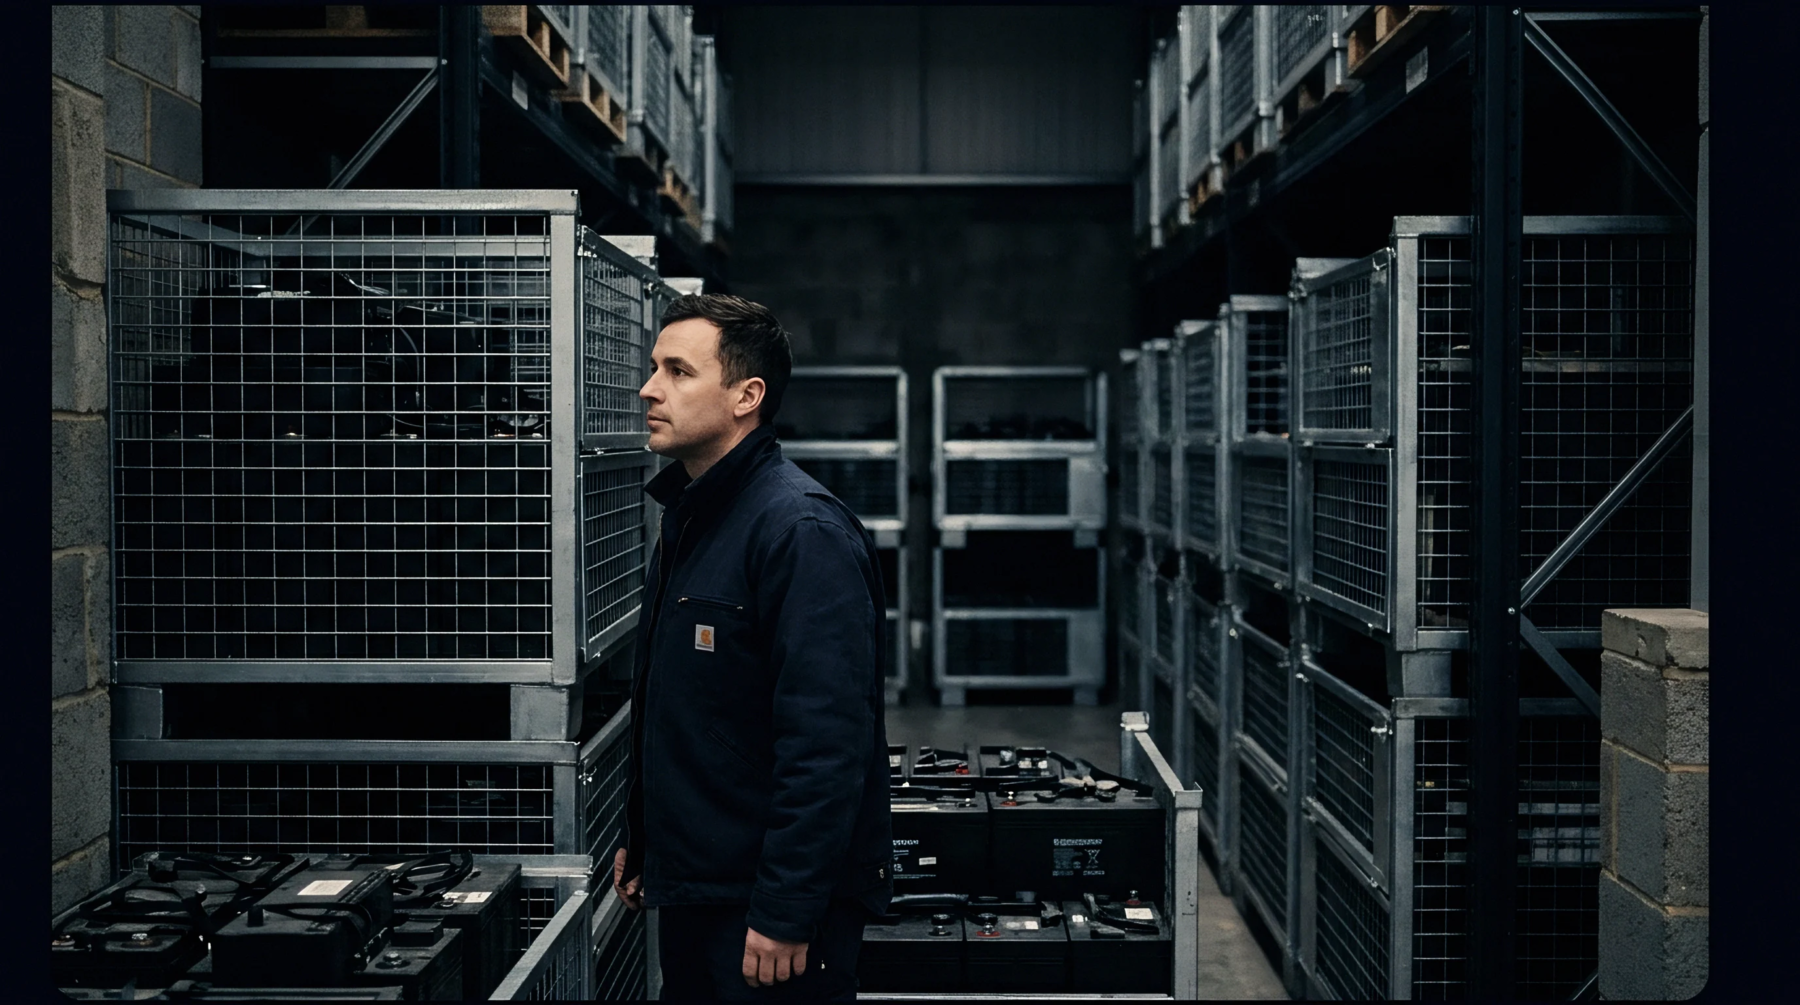
Maintaining this reserve requires close coordination between the finance team and the warehouse managers who track the storage conditions. Storage temperature and state of charge are monitored, as they directly influence the rate of cell degradation and therefore the size of the required reserve. By keeping the warehouse cool and the cells at an optimal state of charge, the rate of physical depreciation can be minimized.
This proactive management reduces the amount of capital that must be locked up in the depreciation fund, freeing up resources for other business activities. It also ensures that the inventory remains viable for assembly.
Procurement Decisions
This financial practice has a major impact on the procurement and inventory turnover strategies of battery manufacturers. Sourcing teams use these write-down estimates to determine the optimal batch sizes for bulk purchases, balancing volume discounts against the cost of aging. Understanding this financial burden encourages the adoption of first-in, first-out inventory systems to minimize the storage time of sensitive cell shipments.
When negotiating long-term supply contracts, buyers must factor in these depreciation costs to evaluate the true lifetime value of the deal. This calculation helps prevent the accumulation of obsolete and degraded stock.